
Quick Answer: 7 LPA In Hand Salary
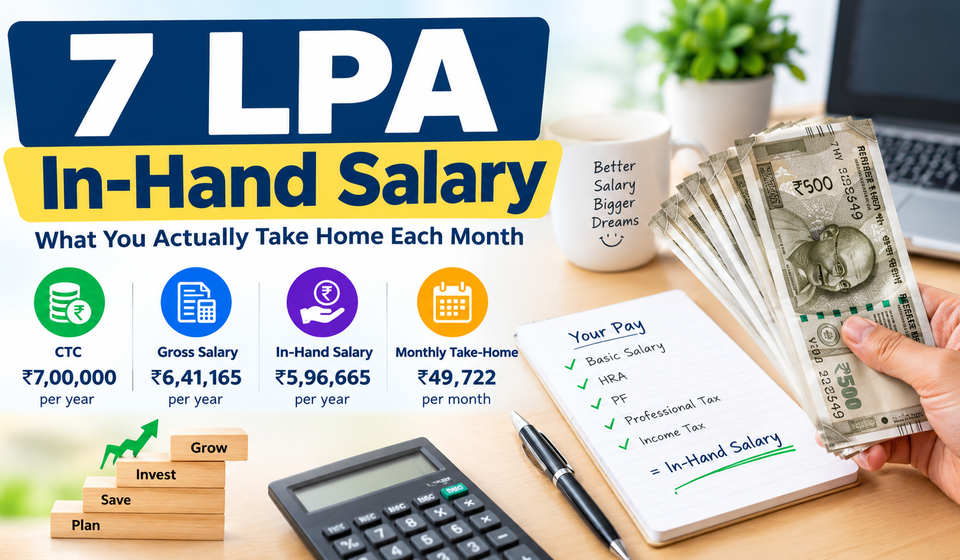
A ₹7,00,000 annual CTC gives an estimated in-hand salary of ₹49,722 per month under the new tax regime for Tax Year 2026–27, assuming an illustrative private-sector structure with PF on full basic and a metro posting in Maharashtra. Annual take-home is ₹5,96,665 — about 85.2% of CTC. Income tax is zero for an eligible resident individual whose taxable income qualifies for the Section 156 rebate under the Income-tax Act, 2025: taxable income after the ₹75,000 standard deduction is ₹5,66,165, below the ₹12,00,000 rebate threshold under Section 156(2). Under the old regime with no deductions, the same CTC produces approximately ₹47,059 per month after an illustrative old-regime tax of about ₹31,962.
Every figure is tied to stated assumptions. Your payslip will differ if your employer’s basic percentage, HRA structure, PF policy, state professional tax, or variable-pay composition differs. The salary structure shown is an illustrative example, not a statutory or industry-wide norm.
7 LPA Meaning: CTC, Gross, and In-Hand Are Not the Same
LPA stands for Lakhs Per Annum. A 7 LPA package means Cost to Company is ₹7,00,000 per year, or ₹58,333 on paper per month. CTC includes employer PF and gratuity provision — employer spend that does not arrive as monthly cash. Employee deductions (employee PF, professional tax, income tax) are subtracted from gross salary to produce in-hand.
Illustrative 7 LPA Salary Breakup (New Regime, Tax Year 2026–27)
This table reconciles exactly to ₹7,00,000. Employer PF and gratuity sit inside CTC and above gross; employee PF and professional tax are deducted from gross.
| Component | Annual (₹) | Monthly equivalent (₹) |
|---|---|---|
| Total CTC | 7,00,000 | 58,333 |
| Basic salary (50% of CTC) | 3,50,000 | 29,167 |
| HRA (50% of basic; illustrative metro assumption) | 1,75,000 | 14,583 |
| Special allowance (balancing figure) | 1,16,165 | 9,680 |
| Less: Employer PF (12% of basic) | (42,000) | (3,500) |
| Less: Employer gratuity provision (estimated at 4.81% of basic) | (16,835) | (1,403) |
| Gross salary | 6,41,165 | 53,430 |
| Less: Employee PF (12% of basic) | (42,000) | (3,500) |
| Less: Professional tax (Maharashtra, male, above ₹10,000/month) | (2,500) | (208 average) |
| Less: Income tax (new regime) | (0) | (0) |
| Estimated annual take-home | 5,96,665 | — |
| Estimated monthly in-hand | — | ₹49,722 |
Reconciliation: ₹3,50,000 + ₹1,75,000 + ₹1,16,165 + ₹42,000 + ₹16,835 = ₹7,00,000. Gross ₹6,41,165 − ₹42,000 − ₹2,500 = ₹5,96,665; ÷ 12 = ₹49,722.
Assumptions — explicitly illustrative, not universal:
- Basic = 50% of CTC (₹3,50,000 / ₹29,167 monthly). An illustrative private-sector structure, not a statutory requirement or a verified industry-wide norm.
- HRA = 50% of basic (₹1,75,000) is a modelling assumption only. The familiar HRA exemption formula — the least of actual HRA received, rent paid minus 10% of salary, and 50% of salary for metro / 40% for non-metro — is an old-regime deduction under Section 10(13A) read with Rule 2A. “Salary” for this formula has a defined tax-law meaning: Basic + DA (where DA forms part of retirement benefits) + turnover-based commission. It is not the employee’s entire gross salary. This exemption does not reduce taxable income in the new-regime calculation shown in the main table. HRA appears in this structure only as a cash component of gross salary; its tax treatment is separate and regime-dependent.
- Employer and employee PF each 12% of full basic (₹42,000 each). The employer’s 12% splits into 3.67% EPF and 8.33% EPS; total employer outgo remains 12%. Full-basic PF is an assumption, not a mandatory outcome; employees already contributing on higher wages may continue under Para 26(6) of the EPF Scheme, 1952, subject to the joint-request process and employer undertaking.
- Gratuity provision is estimated at 4.81% of basic (₹16,835), based on the standard 15/26 monthly-basic formula expressed annually. This is an estimate of employer cost, not a statutory deduction. Gratuity vests only after five years of continuous service.
- Professional tax = Maharashtra male-employee slabs (₹200 × 11 months + ₹300 in February = ₹2,500). Women earning up to ₹25,000 per month are exempt under Maharashtra’s 2023 amendment. Other states differ.
Read More: 6 LPA In Hand Salary / Mail Guard Salary / Enrolled Agent Salary / BSc Nautical Science Salary
New Regime: Zero Tax for Tax Year 2026–27 Under Section 156(2)
Under the Income-tax Act, 2025, the dual “Previous Year / Assessment Year” terminology has been replaced by a single “Tax Year.” For the year beginning 1 April 2026, the label is Tax Year 2026–27. The Union Budget 2026 made no changes to slab rates under either regime; the ₹75,000 standard deduction applies to salaried individuals computing tax under Section 202(1) (the default new regime).
Section 156(2) of the Income-tax Act, 2025 provides that where total income is chargeable under Section 202(1) and does not exceed ₹12,00,000, the assessee is entitled to a deduction of 100% of income-tax payable or ₹60,000, whichever is less. With gross salary of ₹6,41,165, taxable income after the standard deduction is ₹5,66,165, below the ₹12,00,000 threshold. Income tax is therefore zero for an eligible resident individual with no additional taxable income.
Direct official sources:
- Section 156, Income-tax Act, 2025 — full text on Income Tax Department site.
- Deductions from Salary — ₹75,000 standard deduction under Section 202(1).
Old Regime at 7 LPA: Illustrative No-Deduction Case
The old regime is unchanged for this year: basic exemption ₹2,50,000, slabs of 5% / 20% / 30%, and ₹50,000 standard deduction for salaried individuals.
Using the same gross salary of ₹6,41,165 and assuming no other deductions or exemptions:
| Step | Amount (₹) |
|---|---|
| Gross salary | 6,41,165 |
| Less: Standard deduction | (50,000) |
| Taxable income | 5,91,165 |
| Tax before cess | 30,733 |
| Health & Education Cess (4%) | 1,229 |
| Total old-regime tax | 31,962 |
Annual take-home: ₹5,64,703, or ₹47,059 per month (₹5,64,703 ÷ 12 = ₹47,058.58, rounded). That is roughly ₹2,663 lower per month than the new-regime benchmark.
HRA exemption under the old regime: If you opt for the old regime and pay rent, the Section 10(13A) / Rule 2A exemption can reduce taxable income. For this formula, “salary” means Basic + DA (where DA forms part of retirement benefits) + turnover-based commission — not your entire gross salary. This deduction is not available in the new-regime example above. At 7 LPA, the old regime becomes competitive only with substantial eligible deductions; it is not universally better or worse.
Direct official source:
The ₹25,000 PF Ceiling: Coverage Change, Not an Automatic Contribution Change
The EPFO mandatory-coverage wage ceiling rose from ₹15,000 to ₹25,000 per month, effective 17 September 2026 (Gazette Notification S.O. 5109(E); PIB, 23 September 2026). The notification confirms the coverage revision and the associated increase in the maximum EPS contribution at 8.33% (from ₹1,250 to ₹2,083 per month).
What the notification does not do: It does not by itself establish every detail of higher-wage contributions or the joint-option process. Para 26(6) of the EPF Scheme, 1952 allows an employee to contribute on actual higher pay exceeding the statutory ceiling only through a joint request in writing by employer and employee, with the employer undertaking to pay administrative charges on the higher wage. The provision requires the consent of an officer not below the rank of Assistant PF Commissioner. Whether any individual employee’s contribution amount changes depends on the applicable scheme rules, the joint-request process, and the employment arrangement — not on the ceiling notification alone.
Illustrative effect if PF is restricted to the ceiling: at a ₹25,000 wage base, employee PF is ₹3,000 per month (12% of ₹25,000), versus ₹3,500 in the full-basic benchmark (12% of ₹29,167). The ₹500 difference is an outcome only where a higher-wage arrangement is not continued — not a universal automatic change.
Direct official sources:
- EPFO — Para 26(6) joint request form (higher-wage contribution).
- EPFO — Higher Pension FAQs (proof of joint option under Para 26(6)).
- PIB, Ministry of Labour & Employment — ceiling revision, 23 September 2026.
CTC vs Gross vs In-Hand: The Three Layers
| Layer | Annual (₹) | What it is |
|---|---|---|
| CTC | 7,00,000 | Total employer cost, including employer PF and gratuity provision |
| Gross salary | 6,41,165 | Cash earnings before employee deductions |
| In-hand (new regime) | 5,96,665 | After employee PF, PT, and zero income tax |
| In-hand (old regime, no deductions) | ~5,64,703 | After employee PF, PT, and ₹31,962 tax |
The ₹1,03,335 gap between CTC and new-regime annual in-hand consists of employer PF (₹42,000), gratuity provision (₹16,835, estimated), employee PF (₹42,000), and professional tax (₹2,500). Each has a distinct treatment.
What ₹49,722 Per Month Represents for You
At ₹49,722 in-hand, you are in a moderate-to-comfortable band for formal-sector employment in India. This is a personal-budget benchmark, not a national-average or median claim. For verifiable context: TCS’s official All India NQT hiring page lists the Digital cadre at 0–1 year experience with a UG CTC range of ₹7.09–₹7.30 LPA. That makes 7 LPA a common entry point at one large employer, not a national norm.
Whether ₹49,722 feels “good” depends on your city, dependants, rent, and fixed obligations. If fixed costs exceed 40–50% of take-home, the same salary will feel tighter regardless of external comparisons.
Direct official source:
- TCS — All India NQT Hiring page.
FAQs: 7 LPA In Hand Salary
1. Is ₹49,722 the exact in-hand for 7 LPA?
Answer: No. It is a benchmark estimate under stated, illustrative assumptions: 50% basic, HRA at 50% of basic for modelling, PF on full basic, metro Maharashtra posting, male professional-tax slab, and the new regime. Your actual amount depends on your employer’s structure.
2. Does the HRA exemption formula apply in this new-regime calculation?
Answer: No. The formula under Section 10(13A) read with Rule 2A is an old-regime deduction. It uses a defined “salary” base — Basic + DA (where DA forms part of retirement benefits) + turnover-based commission — not entire gross salary. It does not reduce taxable income in the new-regime example above.
3. Does the ₹25,000 PF ceiling automatically change my take-home?
Answer: No. The notification raises mandatory coverage. It does not by itself establish that every employee’s contribution amount changes. Contribution on higher wages beyond the ceiling requires a joint request under Para 26(6) with employer undertaking, subject to the applicable scheme rules and the consent process.
4. Will I pay income tax on 7 LPA?
Answer: Under the new regime, no, for an eligible resident individual with no additional taxable income — taxable income is ₹5,66,165, below the ₹12,00,000 threshold under Section 156(2) of the Income-tax Act, 2025. Under the old regime with no deductions, an illustrative tax of about ₹31,962 applies, reducing monthly take-home to approximately ₹47,059.
5. Can my in-hand be higher than ₹49,722?
Answer: Yes — if PF is capped at the statutory ceiling where a higher-wage arrangement is not continued, if basic is below 50% of CTC, if HRA is structured differently from this illustration, or if part of CTC is structured as reimbursements or variable pay excluded from monthly fixed gross.
6. Which regime is better at 7 LPA?
Answer: The new regime delivers the higher take-home for most 7 LPA earners unless you claim substantial old-regime deductions (HRA, 80C, 80D, home-loan interest). The crossover depends on your actual eligible deductions and your tax-law “salary” for HRA purposes, not on CTC alone.
Final Takeaway
A 7 LPA CTC produces an estimated ₹49,722 monthly in-hand under the new regime for Tax Year 2026–27, with zero income tax for an eligible resident individual under Section 156(2) of the Income-tax Act, 2025. Under the old regime with no deductions, the same CTC yields approximately ₹47,059 per month. The PF ceiling change is real but not an automatic trigger for every employee’s contribution to change; higher-wage contributions depend on the Para 26(6) joint-request process and applicable scheme rules. Use the reconciled breakup to see where each rupee goes — and verify your employer’s PF policy, HRA structure, and state professional tax before treating any benchmark as your exact payslip.
Read More: AME Salary / MNS Salary / IMU CET Salary / Eurasian CEO Salary / Electro Technical Officer Salary