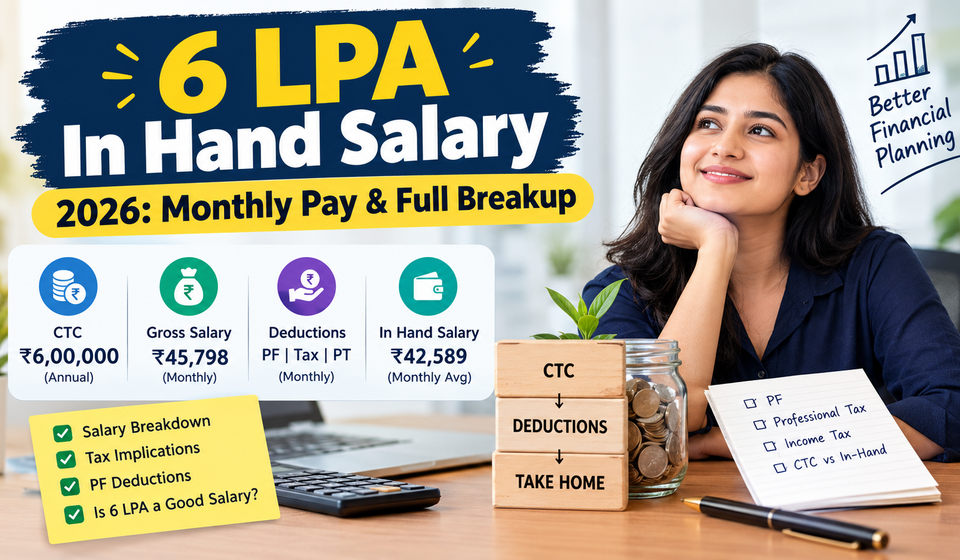

For a ₹6,00,000 annual CTC, the estimated 6 LPA in hand salary is about ₹42,589 per month on an annual-average basis, under the assumptions used in this example. The actual amount depends on the salary structure, PF contribution base, state professional tax and applicable income-tax rules.
The ₹6,00,000 annual package sounds like ₹50,000 per month, but the amount that reaches your bank account is lower because CTC includes employer-side contributions that are never paid as monthly cash, and statutory deductions are made from your gross salary. This guide explains the complete CTC-to-take-home calculation, the impact of the new EPFO wage ceiling, and the factors that can change your actual in-hand amount.
Quick Answer
| Metric | Amount |
|---|---|
| Annual CTC | ₹6,00,000 |
| Monthly CTC | ₹50,000 |
| Gross Monthly Salary (before deductions) | ₹45,798 |
| Estimated Monthly In-Hand (Feb) | ₹42,498 |
| Estimated Monthly In-Hand (Other Months) | ₹42,598 |
| Annual In-Hand | ₹5,11,070 |
| Income Tax (New Regime) | ₹0 |
| Employee PF | ₹3,000/month |
| Professional Tax | ₹200/month (₹300 in Feb) |
Assumptions: Basic salary = 50% of CTC for calculation purposes; PF on full basic salary; metro-city HRA structure; professional tax based on Maharashtra rates for male employees; no variable pay or bonus included; employee is a resident individual eligible for Section 87A rebate with no other taxable income. This is an illustrative example, not a universal calculation.
What Does 6 LPA In Hand Salary Mean?
When an employer offers a package of ₹6 Lakhs Per Annum (6 LPA), this figure refers to the Cost to Company (CTC) — the total amount the company spends on your employment. It includes your basic salary, allowances, employer PF contributions, gratuity provisions, and other benefits.
Your in-hand salary is what remains after subtracting:
- Employer-side components that never come to you as monthly cash: employer PF contribution (12% of basic) and gratuity accrual (~4.81% of basic)
- Statutory employee deductions: your own PF contribution, professional tax, and income tax (TDS)
The gap between CTC and in-hand salary at 6 LPA is approximately ₹7,502 per month for February (when professional tax is ₹300) and ₹7,402 per month for other months (when professional tax is ₹200). This is approximately 15% of the monthly CTC under the assumptions used here.
6 LPA Salary Breakup: From CTC to In-Hand
Here is an illustrative salary breakup for a ₹6,00,000 CTC package. This example assumes basic salary equals 50% of CTC for calculation purposes. The statutory definition of wages can require part of certain excluded components to be added back when those exclusions exceed the prescribed limit. Actual salary structures and statutory calculations may differ.
Annual and Monthly Breakup
| Component | Annual (₹) | Monthly (₹) | Type |
|---|---|---|---|
| Total CTC | 6,00,000 | 50,000 | Gross Package |
| Employer PF (12% of Basic) | −36,000 | −3,000 | CTC Exclusion |
| Gratuity Accrual (~4.81% of Basic) | −14,430 | −1,203 | CTC Exclusion |
| Gross Cash Salary | 5,49,570 | 45,798 | Before Deductions |
| Employee PF (12% of Basic) | −36,000 | −3,000 | Employee Deduction |
| Professional Tax | −2,500 | −208 (avg) | State Deduction |
| Income Tax (New Regime) | −0 | −0 | Tax Deduction |
| Net In-Hand Salary | 5,11,070 | 42,589 (avg) | In Bank Account |
Basic Salary: ₹3,00,000 annually (₹25,000/month)
HRA: ₹1,50,000 annually (₹12,500/month) — metro-city assumption
Special Allowance: ₹99,570 annually (₹8,297.50/month)
Employer PF: ₹36,000 annually (₹3,000/month)
Gratuity: ₹14,430 annually (₹1,202.50/month)
Monthly In-Hand Variation: The in-hand salary is ₹42,598 for months with ₹200 professional tax and ₹42,498 for February when professional tax is ₹300. The annual average is ₹42,589.
This is an illustrative salary breakup. The assumed basic-pay ratio, gratuity provision, PF base and state tax mean this is not a universal calculation for every ₹6 LPA offer.
Why Is There No Income Tax at 6 LPA?
A 6 LPA CTC package is estimated to be effectively tax-free under the new tax regime for FY 2026-27 (AY 2027-28), assuming the employee is a resident individual eligible for the Section 87A rebate and has no other taxable income. The zero-tax estimate uses the new-regime rebate and standard-deduction assumptions stated in this article. Readers should verify the applicable rules for FY 2026-27 (AY 2027-28) with the Income Tax Department before relying on the estimate for tax planning.
- Standard Deduction: Salaried employees get a standard deduction of ₹75,000 under the new regime .
- Taxable Income (Simplified Illustration): Using the gross cash salary from this example (₹5,49,570) minus the ₹75,000 standard deduction, the simplified taxable income is ₹4,74,570. Important: This is a simplified illustration. Actual taxable salary can differ depending on the specific components of your CTC, applicable exemptions (such as HRA under the old regime), and employer contributions. This figure should not be treated as a universal tax calculation.
- Section 87A Rebate: Under the new regime, Section 87A provides a rebate of up to ₹60,000 for resident individuals whose total income does not exceed ₹12,00,000 . Since the simplified taxable income of ₹4,74,570 is well below this limit, the tax liability is estimated to be fully cancelled.
- Result: Estimated income-tax liability: ₹0, subject to the applicable tax rules and your individual circumstances. TDS treatment can depend on payroll calculations and the employee’s tax details.
Old Regime Comparison (Corrected)
Under the old tax regime for FY 2026-27, the standard deduction is ₹50,000. The Section 87A rebate under the old regime is capped at ₹12,500 and is available only where total income does not exceed ₹5,00,000 .
For a 6 LPA employee under the old regime, the tax outcome depends on the taxable income after all applicable deductions and exemptions. The simplified illustration below shows how the old regime may result in zero tax for an eligible resident individual, but this is not guaranteed for every employee:
| Step | Old Regime (Simplified Illustration) |
|---|---|
| Gross Salary | ₹5,49,570 |
| Standard Deduction | −₹50,000 |
| Taxable Income (before other deductions) | ₹4,99,570 |
| Section 87A Rebate (if total income ≤ ₹5,00,000) | Up to ₹12,500 |
| Tax Payable (if eligible for rebate) | ₹0 |
Note: This illustration assumes the employee has no other taxable income and is eligible for the rebate. In practice, eligibility depends on the exact taxable income after all deductions. Employees should calculate their specific liability using the applicable rules. The result is an estimate based on the stated tax assumptions, not a guaranteed tax outcome.
Read More: 2 LPA In Hand Salary / 3 LPA In Hand Salary / 4 LPA In Hand Salary / 5 LPA In Hand Salary
Impact of the New EPFO Wage Ceiling (September 2026)
The Central Government has enhanced the statutory monthly wage ceiling for mandatory EPFO coverage from ₹15,000 to ₹25,000, effective 17 September 2026, as notified vide Gazette Notification S.O. 5109(E) issued by the Ministry of Labour and Employment .
What Changed?
The following figures are illustrative calculations at a ₹25,000 contribution base versus a ₹15,000 contribution base. They show the maximum contribution where the wage ceiling is the applicable base. They are not a universal result for every employee.
| Illustrative Contribution Base: ₹15,000 vs ₹25,000 | Old Ceiling (₹15,000) | New Ceiling (₹25,000) |
|---|---|---|
| Employee PF (12% of ceiling) | ₹1,800/month | ₹3,000/month |
| Employer PF (12% of ceiling) | ₹1,800/month | ₹3,000/month |
| EPS Contribution (8.33%) | ₹1,249.50/month | ₹2,082.50/month |
| Possible maximum difference in employee PF deduction | — | Up to ₹1,200/month |
At 6 LPA, your basic salary is ₹25,000 per month, which is exactly at the new ceiling. The key point is that the ceiling for mandatory coverage is not automatically the contribution base for every existing member.
- For employees who were already contributing PF on full basic salary (₹25,000/month), there is no change. Their contribution was already ₹3,000/month.
- For employees whose EPF and allied contributions were hitherto restricted to the ₹15,000 ceiling, the wage ceiling for monthly contributions shall be enhanced to ₹25,000 per month or the actual salary/wages, whichever is lower, subject to applicable statutory provisions and scheme rules .
- For employees newly eligible for enrolment (those earning between ₹15,000 and ₹25,000 who were previously excluded), enrolment is now possible provided they fulfil all other eligibility conditions .
- EPS Contribution: Where applicable, the maximum contribution towards EPS shall be calculated at 8.33% of ₹25,000, instead of 8.33% of ₹15,000.
The actual PF deduction depends on the employer’s payroll policy and the employee’s existing PF membership and contribution arrangement. Employees should verify their specific PF contribution base with their employer or PF passbook. For official details, refer to the EPFO wage ceiling announcement .
What Your Monthly Payslip Will Look Like
Here is an illustrative payslip structure for a 6 LPA employee with PF on full basic salary:
| Payslip Line | Monthly Amount (₹) |
|---|---|
| Basic Pay | 25,000 |
| HRA | 12,500 |
| Special Allowance | 8,298 |
| Gross Earnings | 45,798 |
| Employee PF | −3,000 |
| Professional Tax (Feb) | −300 |
| Income Tax (TDS) | ₹0 |
| Net Pay (Feb) | 42,498 |
| Net Pay (Other Months) | 42,598 |
Note: The split between HRA and special allowance varies by employer. The total gross earnings and net pay remain consistent.
Key Factors That Affect Your 6 LPA In Hand Salary
1. Basic Salary Percentage
This example assumes basic salary equals 50% of CTC for calculation purposes. The statutory definition of wages can require part of certain excluded components to be added back when those exclusions exceed the prescribed limit. Actual salary structures and statutory calculations may differ.
2. PF Contribution Policy
At a basic salary of ₹25,000 per month, PF at 12% of the full basic salary equals ₹3,000 per month. The actual contribution may differ if a different contribution base applies under the employee’s PF arrangement.
3. Professional Tax
Professional tax varies by state. The calculation here uses Maharashtra rates for male employees: ₹200 per month for 11 months and ₹300 in February, totalling ₹2,500 per year . Women earning up to ₹25,000/month are exempt from professional tax in Maharashtra .
4. Variable Pay and Bonus
If your 6 LPA CTC includes performance-linked variable pay or annual bonus, your monthly in-hand salary may be lower because these components are not paid monthly. This guide assumes no variable pay.
5. City Tier
HRA rates differ between metro and non-metro cities. Metro cities (Delhi, Mumbai, Kolkata, Chennai) typically have HRA at 50% of basic, while non-metro cities use 40%. This affects the gross salary composition but not the net in-hand figure in this example, since the total gross remains the same.
Is 6 LPA a Good Salary in India?
Whether a 6 LPA package is considered a good salary depends on several factors:
- Location: In tier-2 and tier-3 cities, a 6 LPA salary often provides a comfortable lifestyle. In metro cities, the same amount may feel tighter, especially with higher rent and living costs.
- Household Size: A single person can manage comfortably on 6 LPA in most cities. A family with dependents may find it more challenging without additional income.
- Rent and Housing: If you live in shared accommodation or with family, your disposable income is higher. Independent accommodation in a metro city can consume a significant portion of your take-home.
- Benefits: Employer-provided health insurance, meal cards, and other benefits can effectively increase your total compensation beyond the CTC figure.
- Career Stage: For a fresher, 6 LPA is a strong starting point. For someone with several years of experience, it may be below market expectations depending on the industry.
Rather than relying on a single “good salary” figure, compare your take-home against your actual monthly expenses and financial goals.
6 LPA vs 7 LPA: What Changes?
A move from 6 LPA to 7 LPA adds approximately ₹7,133 per month to your in-hand salary, assuming the same salary structure and PF policy. The 7 LPA calculation below uses the same proportional assumptions as the 6 LPA model: basic salary at 50% of CTC, PF at 12% of basic, and gratuity at approximately 4.81% of basic.
| Metric | 6 LPA | 7 LPA |
|---|---|---|
| Annual CTC | ₹6,00,000 | ₹7,00,000 |
| Monthly CTC | ₹50,000 | ₹58,333 |
| Basic Salary (monthly) | ₹25,000 | ₹29,167 |
| Employer PF (12% of Basic) | ₹3,000 | ₹3,500 |
| Gratuity Accrual (~4.81% of Basic) | ₹1,203 | ₹1,403 |
| Gross Monthly Salary | ₹45,798 | ₹53,430 |
| Employee PF | ₹3,000 | ₹3,500 |
| Professional Tax (avg) | ₹208 | ₹208 |
| Income Tax | ₹0 | ₹0 |
| Monthly In-Hand (avg) | ₹42,589 | ₹49,722 |
Note: The 7 LPA figures follow the same assumptions as the 6 LPA model. Minor variations may occur due to rounding. This is an illustrative comparison, not a universal calculation.
Frequently Asked Questions
1. Is 6 LPA tax-free in India?
Answer: Under the new tax regime for FY 2026-27 (AY 2027-28), a 6 LPA CTC package is estimated to be effectively income-tax-free for a resident individual eligible for the Section 87A rebate with no other taxable income. After the ₹75,000 standard deduction, the simplified taxable income is approximately ₹4,74,570, which is below the ₹12,00,000 limit for the rebate. This is an estimate based on the stated assumptions, not a guaranteed tax outcome. Verify the applicable rules with the Income Tax Department .
2. How much is 6 LPA per month?
Answer: A 6 LPA CTC equals ₹50,000 per month in CTC terms. Your gross monthly salary before deductions is approximately ₹45,798, and your net in-hand salary is approximately ₹42,589 (annual average) after PF and professional tax deductions.
3. What is the difference between CTC and in-hand salary at 6 LPA?
Answer: CTC is the total cost to the company, which includes employer PF and gratuity. In-hand salary is the cash credited to your bank account after all deductions. At 6 LPA, the difference is approximately ₹7,400 to ₹7,500 per month, depending on the professional tax month.
4. Does the new EPFO wage ceiling affect my 6 LPA salary?
Answer: It depends on your existing PF contribution arrangement. If your employer had previously capped PF at the ₹15,000 ceiling, your PF contribution base may increase to ₹25,000 (or actual salary, whichever is lower), potentially reducing your take-home by up to ₹1,200 per month. However, if your employer already contributed PF on full basic salary, there is no change. The ceiling for mandatory coverage is not automatically the contribution base for every existing member. For official details, refer to the EPFO wage ceiling announcement .
5. Can I opt out of PF to get a higher in-hand salary?
Answer: Employees who are already covered by EPF generally cannot simply stop contributions to increase take-home pay. Rules for a person joining employment for the first time can depend on membership history, wages and the applicable provisions. Confirm your eligibility with your employer or EPFO rather than assuming that opting out is available.
6. What is the annual take-home for 6 LPA?
Answer: The annual in-hand salary for a 6 LPA package is approximately ₹5,11,070, which is about 85.2% of your total CTC.
Final Takeaway
A 6 LPA in hand salary of approximately ₹42,589 per month (annual average) is an illustrative benchmark under the assumptions above for FY 2026-27 (AY 2027-28) under the new tax regime. The key drivers of this figure are:
- Zero income tax (estimated) due to the Section 87A rebate (up to ₹60,000) and ₹75,000 standard deduction
- PF contribution of ₹3,000/month (12% of ₹25,000 basic salary)
- Professional tax of ₹200/month (₹300 in February, state-dependent)
- Employer PF and gratuity of approximately ₹4,203/month held within CTC
Your actual in-hand amount can vary based on your employer’s PF policy, salary structure, and professional tax rates in your state. Always verify your specific structure in your offer letter or first payslip. For official rules, refer to the Income Tax Department , EPFO , and the Maharashtra GST Department .
Read More: Mail Guard Salary / Enrolled Agent Salary / BSc Nautical Science Salary / IMU CET Salary